
Achieng knows the rhythm of a busy neighbourhood pharmacy. The first customer arrives before the morning shelves are fully checked. A delivery rider brings a supplier invoice. Someone pays by M-Pesa, another customer requests a receipt, and a colleague notices a product approaching its expiry date. Each activity matters to the business, but each also leaves a financial record that someone must handle correctly.
That is why Pharmacy Bookkeeping in Kenya deserves as much attention as stock availability and customer service. Achieng’s Community Chemist is a fictional example of a properly licensed pharmacy run by a qualified pharmaceutical professional. Her situation illustrates the practical pressures facing independent chemists and the ways organised accounting support can help owners make informed decisions. It does not describe a verified FedhaTrac client or promise a particular financial result.
As the chemist grows, Achieng needs to understand not just what comes through the till but what remains after medicine purchases, salaries, rent, losses and other operating costs. Pharmacy Bookkeeping in Kenya connects those moving parts. With FedhaTrac supporting the bookkeeping, reconciliations and management-reporting work, Achieng can devote more management attention to customers, stock quality and her professional responsibilities.
Achieng’s Growing Chemist Needs More Than a Full Till
At first, Achieng recorded sales in a notebook and stored supplier receipts in a drawer. That approach became unreliable as the chemist added new product lines, more transactions and an additional staff member. A good trading day looked impressive until rent, supplier credit and replacement stock became due. Cash in the bank did not always mean the business had earned a profit.
Pharmacy Bookkeeping in Kenya provides a way to distinguish daily activity from financial performance. The chemist needs a sales record, a purchasing record, a stock record, a list of what is owed and a reconciliation of actual payment balances. Each record answers a different question, and none should be expected to do the work of all the others.
Record Every Sale and Keep Payment Channels Separate
Kenyan pharmacy staff checking a daily receipt, till figures and bookkeeping records beside a laptop.
A pharmacy may receive cash, M-Pesa, card and bank payments during the same shift. Achieng needs sales totals that agree with transactions processed through the point-of-sale system and the money actually received. Pharmacy Bookkeeping in Kenya begins with recognising a sale correctly, not merely counting cash at closing time.
At the end of each day, the till report can be compared with cash counted, mobile-money collections and card settlement records. Returns, genuine cancellations and permitted refunds need distinct entries rather than being hidden inside sales totals. Any difference should be investigated and documented while the transaction is still easy to remember.
An orderly daily close
A simple close includes opening float, total sales by payment method, refunds, payment charges, cash deposited and unexplained variances. Achieng can assign an employee to prepare the figures and another authorised person to review them. Staff should retain customer and invoice information only as necessary and protect confidential health information from wider finance reports.
FedhaTrac can help build the underlying bookkeeping routine and check its consistency with Achieng’s records. This is the foundation of dependable Pharmacy Bookkeeping in Kenya, especially for a chemist handling numerous small transactions.
Reconcile M-Pesa and Bank Statements Without Double-Counting Revenue
A customer pays KSh 2,000 through the chemist’s till. Later, that money is transferred from M-Pesa to the bank. These movements do not create two separate sales. Yet treating every credit on both statements as new income is a common bookkeeping error.
Pharmacy Bookkeeping in Kenya requires each original customer receipt to be matched with the sale, while the later movement between accounts is recorded as an internal transfer. Business transaction charges, reversals and supplier payments must also be entered in the right categories. Otherwise, sales may be overstated and closing balances may not agree.
Achieng can use the guidance in FedhaTrac’s M-Pesa bookkeeping guide alongside a regular bank reconciliation process. Reconciliation should not be an exercise in forcing the figures to agree; unexplained differences should be traced back to the missing receipt, duplicate entry, fee or timing item.
Track Medicine Purchases, Inventory Value and Product Movement
Qualified pharmacy professional checking medicine stock against a tablet in a Kenyan community chemist.
For a pharmacy, shelves represent substantial working capital. Money tied up in slow-moving products cannot simultaneously pay suppliers or purchase faster-selling stock. Pharmacy Bookkeeping in Kenya therefore needs to connect inventory quantities with invoice costs and actual sales.
Achieng’s inventory register can capture product description, supplier, quantity received, purchase cost, batch details, expiry date where relevant, quantity sold and remaining units. Pharmacy professionals must remain responsible for the storage, quality and suitability of products. The finance records should reflect verified stock movements rather than making clinical decisions.
Regular counts are useful because the numbers recorded in a computer may differ from what is physically available. A breakage, return, stock transfer, dispensing adjustment or unrecorded sale can create a variance. Pharmacy Bookkeeping in Kenya helps quantify that difference, but Achieng and appropriately authorised staff must investigate the operational cause.
This approach also supports better purchasing. She can ask whether a product deserves more shelf space based on demand and margin, while avoiding the mistake of buying large quantities purely because a supplier offered a discount. The financial implications of overstocking become easier to see when the books reflect stock value accurately.
Control Short-Dated, Expired and Returned Medicines
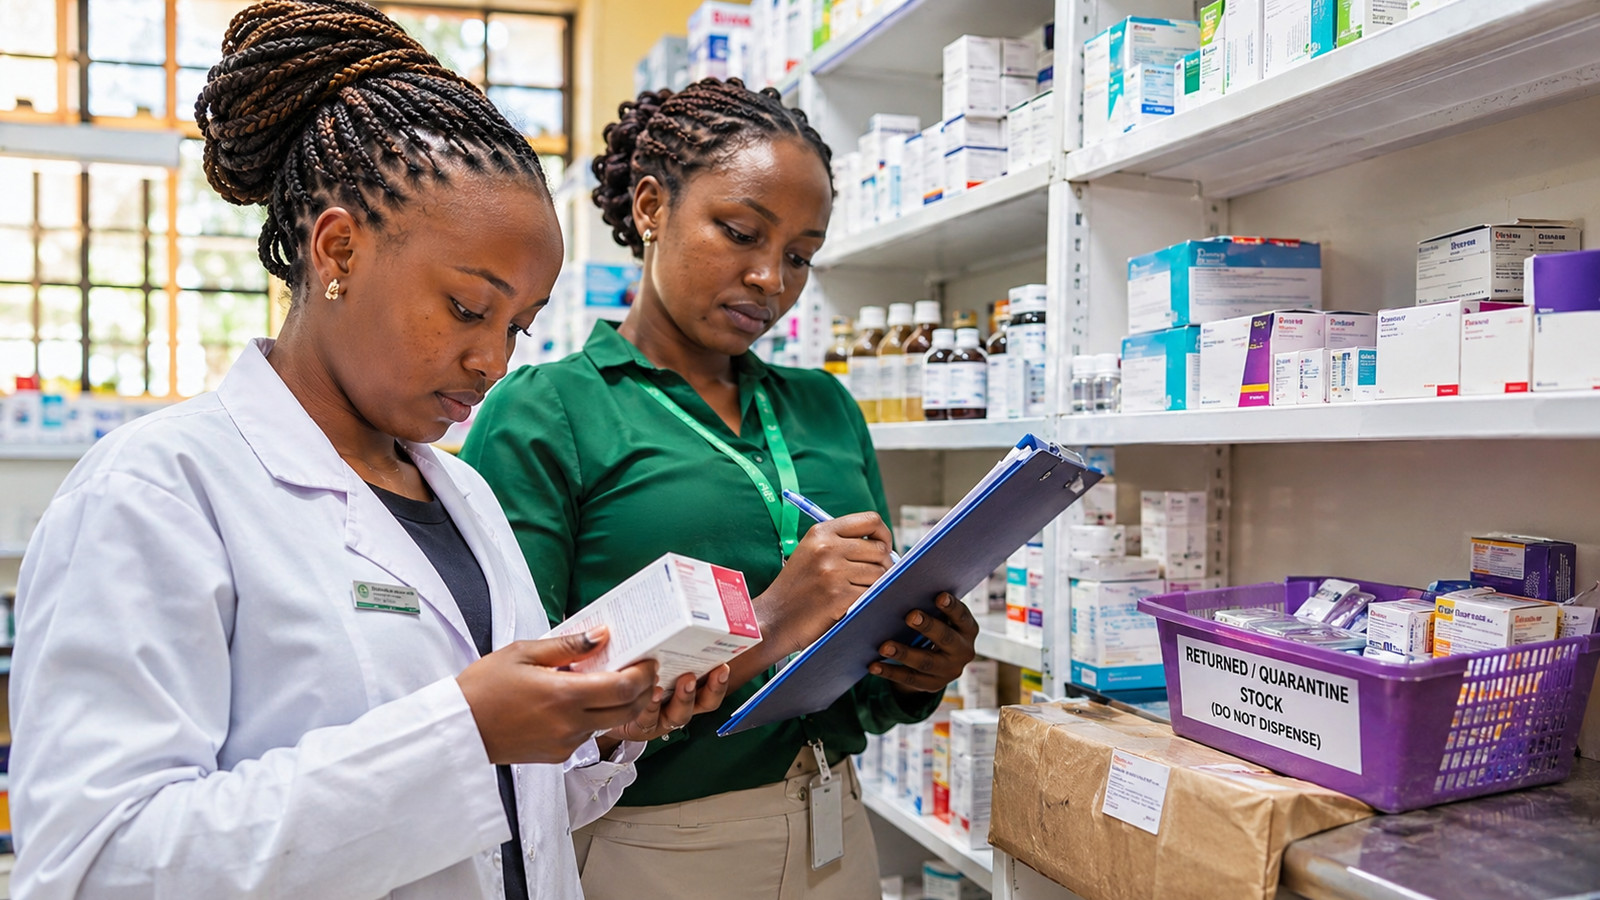
Kenyan pharmacy staff checking medicine expiry information and documenting quarantined stock.
An item approaching expiry is not the same as usable stock with a long remaining shelf life. Expired medicines cannot simply be sold to recover the purchase cost. The Pharmacy and Poisons Board recommends measures such as first-expiry-first-out stock rotation and appropriate handling of pharmaceutical waste. Licensed professionals remain responsible for quarantine, returns and lawful disposal under applicable requirements.
Pharmacy Bookkeeping in Kenya should reflect the financial consequences separately. Achieng can keep a controlled list of near-expiry items, products returned to suppliers, credit notes received and stock written off after appropriate authorisation. This creates a record of the value lost rather than allowing the loss to disappear inside an unexplained stock adjustment.
If a supplier agrees to accept eligible short-dated products, the return should be documented and the related supplier credit recorded. If disposal is necessary, the relevant regulatory and waste-management procedures take priority. Pharmacy Bookkeeping in Kenya captures the cost, but bookkeeping is not a substitute for professional pharmaceutical controls.
By reviewing these figures each month, Achieng can identify whether excessive ordering, weak stock rotation or poor demand forecasting is repeatedly reducing her margin. The financial report gives her a reason to investigate; it does not authorise anyone to dispense unsuitable products.
Keep Supplier Invoices, Credit Notes and Payment Dates Organised
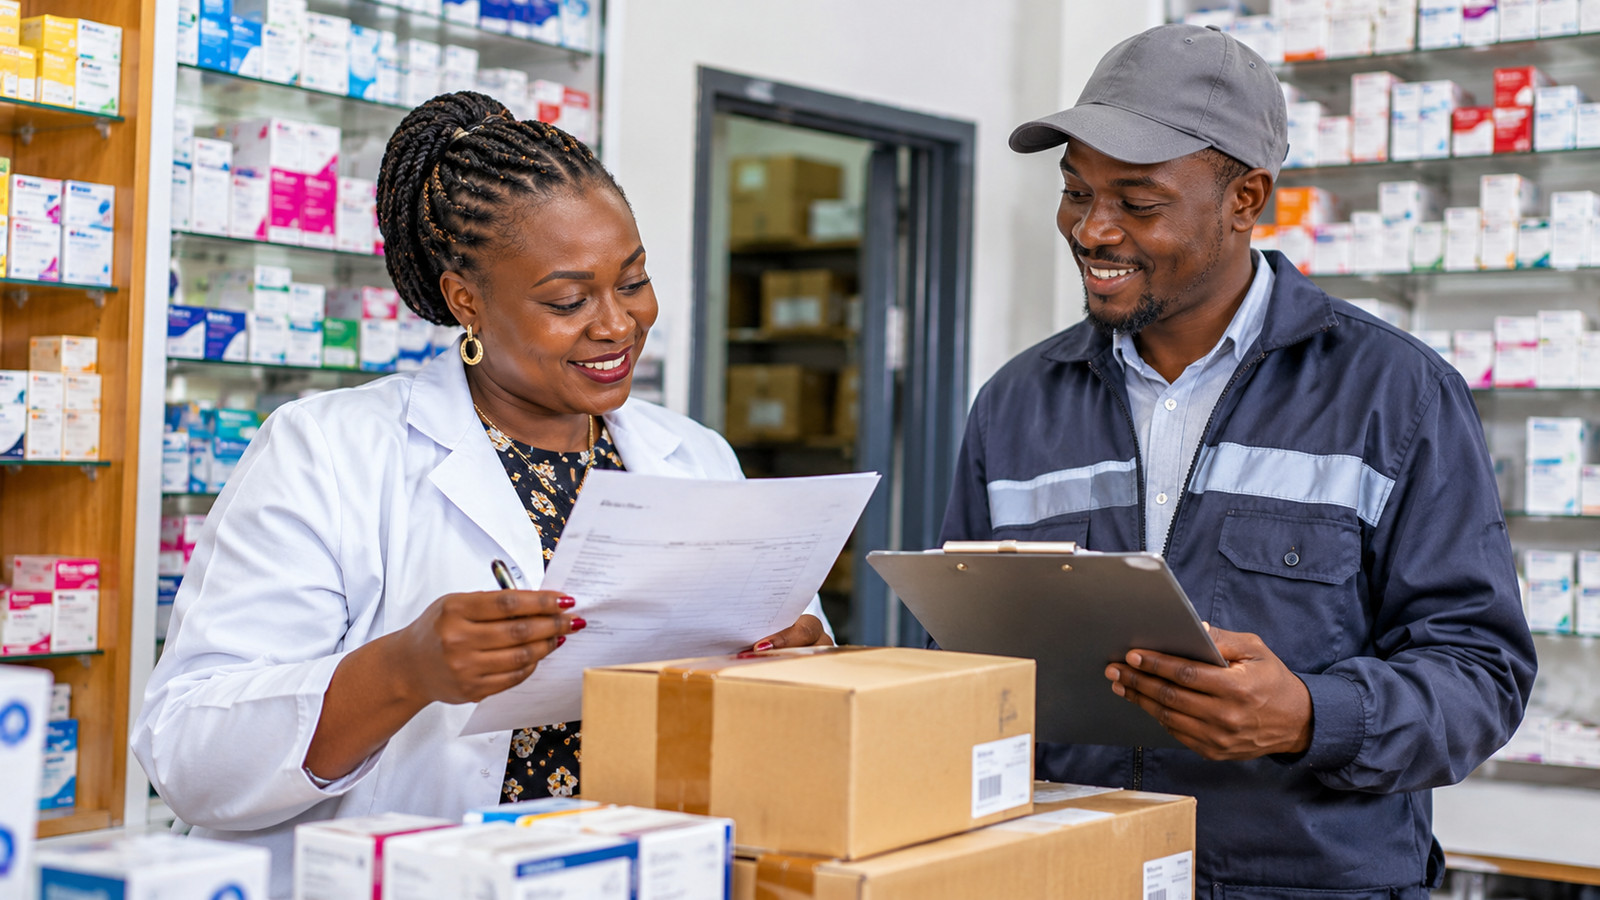
Achieng reviewing pharmacy delivery paperwork and supplier invoices with a delivery worker.
A busy chemist may buy from several wholesalers, each with different delivery schedules and payment terms. Without a supplier ledger, Achieng can lose track of part-payments, returns and invoices still outstanding. A strong Pharmacy Bookkeeping in Kenya process should make every payable traceable to a genuine purchase.
For each delivery, the responsible staff should compare the order, delivery note, items received and supplier invoice. Any shortage, damage or discrepancy should be resolved through the supplier and recorded appropriately. FedhaTrac can then help organise the approved invoice, payment entry and outstanding balance.
An aged payables report is especially useful. It shows which bills are due soon, which are overdue and which are disputed. Achieng can plan payments without accidentally paying the same invoice twice. FedhaTrac’s expense tracking and invoicing guide explains why consistent supporting documentation improves financial control.
Understand Gross Margin Before Judging a Product’s Success
A fast-selling product can be less profitable than it appears if its purchase cost has risen or its discounts are excessive. Pharmacy Bookkeeping in Kenya helps Achieng separate revenue, direct cost of goods sold and operating expenses to see where the money is actually going.
Consider a strictly illustrative example: a non-specific product costs KSh 640 to acquire and is sold for KSh 900, before any applicable tax treatment or other direct adjustments. The gross profit is KSh 260, and the gross margin is about 28.9% of the sale price. This does not mean the chemist has earned KSh 260 in net profit; rent, staffing, payment fees, losses and other overheads still need to be considered.
Achieng should review margins by sensible product category while keeping pricing and supply decisions consistent with applicable laws and professional requirements. Some products require different VAT treatment, so a simple gross-margin example must never be mistaken for a tax-inclusive pricing rule.
FedhaTrac’s explanation of gross profit versus net profit can support that analysis. Pharmacy Bookkeeping in Kenya gives Achieng the detail to decide whether her chemist is truly improving, not simply selling more units.
Capture Rent, Staffing and Other Day-to-Day Costs
The pharmacy does not stop spending when deliveries are complete. There may be premises rent, electricity, internet, wages, security, cleaning, packaging, payment charges, refrigeration maintenance and approved professional licence-related fees. Pharmacy Bookkeeping in Kenya should classify these costs consistently so Achieng understands the true cost of keeping the business open.
Staffing costs need careful documentation, including approved compensation records and statutory deductions where applicable. FedhaTrac can help organise financial records and tax-compliance information, but the chemist must maintain appropriate employment processes and professional supervision. A bookkeeping service should not be presented as the pharmacy’s clinical manager or as a substitute for its licensed personnel.
Personal withdrawals also need their own accounting treatment. When Achieng buys household groceries from the pharmacy’s funds, the books should not disguise the payment as a business expense. The small-business bookkeeping best-practices guide offers a broader framework for keeping personal and business money separate.
With these categories visible, Pharmacy Bookkeeping in Kenya helps spot rising operating costs before they consume the margin from successful sales.
Plan Cash Flow Before Ordering More Stock
Profit and cash are related, but they are not interchangeable. Achieng may have profitable sales on paper and still face a short-term shortage when a large supplier invoice becomes due. Pharmacy Bookkeeping in Kenya helps her plan around payment dates, restocking needs and predictable operating costs.
A weekly cash forecast should start with actual available balances, add expected collections and deduct anticipated payments. It should distinguish confirmed commitments from estimates. For example, if a supplier payment is due on Friday, planning to settle it from uncertain weekend sales is risky. Achieng may instead need to adjust the purchase schedule or protect enough cash earlier in the week.
A well-organised cash-flow statement supports that conversation. Pharmacy Bookkeeping in Kenya can highlight the cash tied up in stock and show whether the chemist is becoming more resilient or simply taking on larger financial commitments.
Use Monthly Reports to Run a Better Community Chemist
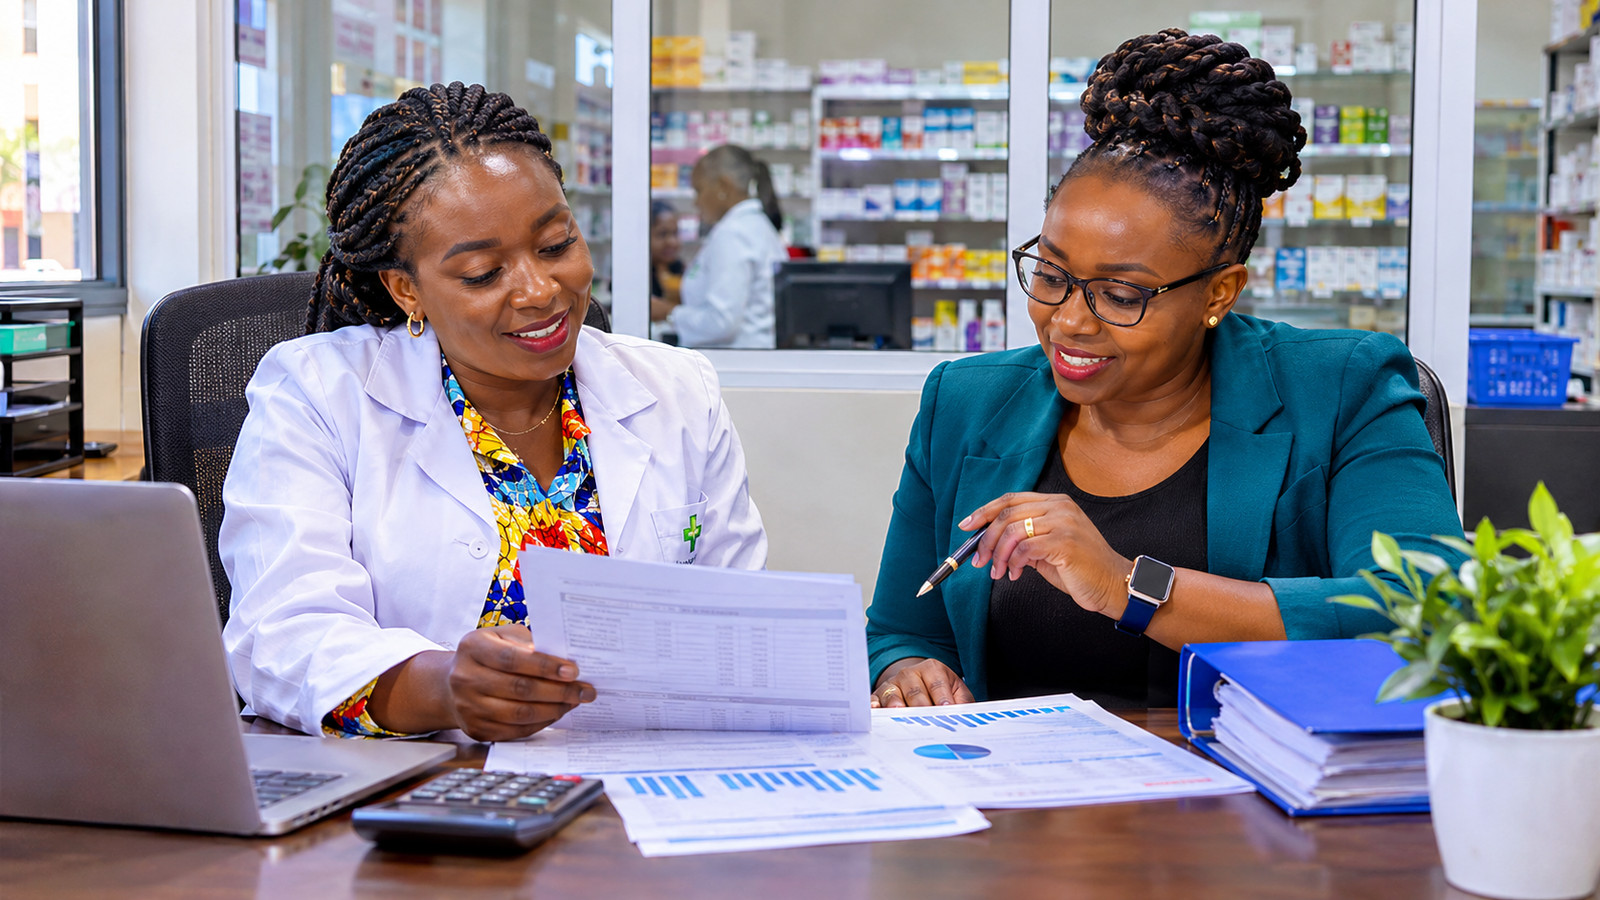
Kenyan pharmacist and finance adviser reviewing chemist expenses and management reports.
By month-end, Achieng should have more than a box of receipts. A useful report can show sales, cost of goods sold, gross profit, operating expenses, supplier payables, stock adjustments, cash balances and relevant trends. Pharmacy Bookkeeping in Kenya brings those figures together so that management can compare actual performance with an agreed budget.
FedhaTrac can help prepare financial summaries, investigate unusual variances and identify areas needing management attention. Achieng might notice growing sales but shrinking gross margin, or good profit but rising supplier balances. Each finding leads to a different question and a different action.
A simple monthly meeting can review what changed, why it changed, who is responsible for follow-up and when the next review will occur. Pharmacy Bookkeeping in Kenya then becomes a regular decision-making system, not a document prepared only when a lender or tax authority asks for it.
Tax Records and eTIMS: Get the Details Right
Business owners must understand the invoicing and tax obligations that apply to their particular activities. KRA states that persons engaged in business generally need to onboard eTIMS and issue electronic tax invoices, subject to the relevant rules and exceptions. From the 2026 year of income, its guidance places strong emphasis on properly supported declared income and expenses, including applicable electronic-invoice documentation.
Pharmacy Bookkeeping in Kenya should therefore retain invoices, supplier records, transaction evidence and reconciliations that are consistent with the business’s tax position. Achieng can review the official KRA eTIMS guidance and FedhaTrac’s practical eTIMS guide for Kenyan businesses.
VAT requires particular care. Kenya’s VAT rules distinguish exempt supplies, zero-rated supplies and supplies subject to the standard rate; medicine and other pharmacy product classifications must be checked against current law for the actual product. It would be wrong to assume that every item in a chemist attracts the same VAT treatment. Registration and input-tax entitlement also depend on the applicable taxable supplies and legal conditions.
FedhaTrac can support record preparation and compliance organisation, while an appropriately qualified tax adviser should confirm the treatment of unusual products and transactions. Pharmacy Bookkeeping in Kenya supports compliance through reliable evidence; it does not replace legal interpretation.
Licensed Pharmacy Practice Is Separate From Financial Bookkeeping
Achieng’s pharmacy must meet the requirements of the Pharmacy and Poisons Board for premises and professional practice. The Board publishes guidance on licensing, registration, storage and pharmaceutical waste. The appropriate licensed practitioner is responsible for professional pharmaceutical decisions, not an external bookkeeper.
This distinction matters. Pharmacy Bookkeeping in Kenya can account for inventory losses, supplier balances and licence-related costs, but it cannot decide whether a medicine is suitable to dispense, whether a batch should be recalled or how regulated waste may be handled. The business needs both a sound financial system and effective professional controls.
Achieng should also keep patient-related or prescription information outside ordinary management reports unless its use is legally justified and necessary. Financial reports usually need aggregated figures rather than identifiable clinical details. Respecting that boundary supports responsible, professional operations.
A Practical 30-Day Bookkeeping Reset for Achieng
Improvement does not require a dramatic overnight transformation. Pharmacy Bookkeeping in Kenya can be strengthened through a focused month of consistent routines.
During the first week, Achieng can gather current bank and M-Pesa statements, sales records, supplier invoices, outstanding bills and stock reports. In the second week, she can reconcile payment channels and investigate unexplained entries. In the third week, her authorised pharmacy team can check physical stock and expiry records while the financial entries are aligned with verified movements. In the fourth week, management can review a first clean income-and-expense summary and agree on the next month’s control checklist.
Frequently Asked Questions About Pharmacy Bookkeeping in Kenya
Does a small chemist really need monthly bookkeeping?
Yes, regular records are valuable even when the pharmacy is small. Pharmacy Bookkeeping in Kenya helps identify sales discrepancies, stock losses, unpaid suppliers and unexpected cash shortages while they are still manageable. The depth of reporting can match transaction volume and complexity.
Can FedhaTrac handle medicine dispensing or professional licensing?
No. FedhaTrac’s role in this story concerns bookkeeping, financial reporting and related accounting or tax-support records. The pharmacy’s appropriately licensed professionals remain responsible for clinical dispensing, premises compliance, medicine storage and regulated disposal.
Should expired stock still appear as saleable inventory?
No. Expired or otherwise unsuitable products should be segregated and handled according to applicable professional requirements. Financial records must also reflect authorised returns, credits or write-offs. Pharmacy Bookkeeping in Kenya records the value affected without authorising the product’s use.
What should Achieng review every month?
She should review reconciled sales, bank and M-Pesa balances, supplier payables, inventory adjustments, gross margin, operating expenses and near-term cash commitments. A concise report and follow-up actions are more useful than a large report nobody reads.
Grow a Trustworthy Chemist With Clear Financial Records
Achieng’s future depends on more than the number of customers walking through her door. Growth should be supported by reliable records, responsible stock controls and timely financial decisions. Pharmacy Bookkeeping in Kenya makes that possible by turning daily activity into information she can actually use.
FedhaTrac helps Kenyan businesses organise bookkeeping, reconciliations and financial reporting so owners can see what is happening behind the sales counter. If your chemist’s supplier invoices, payment records or monthly accounts are becoming difficult to manage, visit FedhaTrac or contact support@fedhatrac.com to discuss appropriate financial-record support for your business.


